AI Companions and Teens What Parents Need to Know
AI is no longer just helping teens with homework. Some young people are using chatbots for friendship, emotional support, romantic role-play, and conversations they do not feel...
Why isn’t my child listening? Take the Quiz NOW!
In this episode, Sue and Randee talk about practical ways to help kids earn money by creating value, make spending decisions with their own money, build saving habits, and begin learning about investing. The goal is not to raise children who copy your financial choices. It is to give them enough experience to make thoughtful choices of their own while the stakes are still small.
Is your child good with money, or simply good at getting money from you?
Most families have some kind of system. Some kids receive a weekly allowance. Some are paid for chores or good grades. Others get money when they ask, when a birthday rolls around, or when a parent sends a quick Venmo on the way out the door.
There is no single system that works for every family. What matters is what children learn from the way money moves through your home. Every time money changes hands, you have an opportunity to teach value, choices, responsibility, and independence.
The goal is bigger than helping a child understand what one dollar is worth. We want kids to understand what money can do. It can be earned, saved, spent, invested, shared, or used to solve a problem. Knowing how to get money is one skill. Knowing what to do with it is another.
The first lesson is simple: money is generally exchanged for value. That does not mean children should be paid for everything they do.
Making the bed, picking up personal belongings, helping with ordinary cleanup, and taking care of their own things are part of living in a family. Congratulations, kid. You are part of the operation. Basic responsibilities do not automatically require a paycheck.
Extra value is different. A child may save you time, take on a job you dislike, solve a problem, improve a process, or create something another person wants. That is where earning money can become a meaningful lesson rather than a transaction attached to a chore chart.
Instead of always deciding which chores are available and what each one pays, invite your child to notice what would be useful. Ask: What can you take off my plate? What problem can you solve? What could you improve? What can you create that someone else would value?
Sue saw this play out when one of her children discovered that she highly valued a back rub and having someone play with her hair. He was willing to spend the time, and she was delighted to pay him. He figured out how to create value for a specific customer, even if that customer happened to be Mom.
An older child might shovel snow, mow lawns, wash cars, or complete a job for a neighbor. If the child uses your equipment, introduce the idea of overhead. What does it cost to rent the lawn mower or buy supplies? What must the child charge to earn a profit? If payment comes later, what does it mean to send an invoice and follow up?
These experiences teach children to identify needs, take initiative, negotiate, and understand that completing work and receiving payment are not always the same step.
Money does not have to be tied only to household labor. You can also create opportunities that support growth.
Instead of paying for a grade, you might pay a child to choose a book and talk with you about what they learned. If speaking to adults makes your child nervous, perhaps ordering for the family at a restaurant is worth something. A useful idea that saves the family time or money may also deserve a reward.
The larger lesson is that their ideas have value. Their knowledge has value. Their courage, initiative, creativity, and ability to solve a problem have value.
Real-world value is not always fixed. A job can be worth more or less depending on timing, urgency, supply, and demand.
Cleaning the yard might normally be a ten-dollar job. If guests are arriving in an hour and you need it done immediately, you may gladly pay twenty. If your child suddenly needs money tonight, the urgency belongs to them and you may offer five. It is the same job, but the circumstances have changed.
You do not need to deliver an economics lecture. A few ordinary negotiations can teach children that value depends on who needs what, how badly they need it, and when they need it. Both sides can benefit when they agree on a fair exchange.
Once children earn money, the next lesson begins: spending their own money feels completely different from spending yours.
There is a huge difference between asking, ‘Will you buy this for me?’ and wondering, ‘Do I want this badly enough to spend thirty dollars of my own money?’ When the money belongs to a child, the pause becomes useful. How much do I have? What will be left? Is this worth it? Is there something else I want more?
That internal calculation is exactly what we want children to practice. They are developing their own sense of value instead of borrowing ours.
Your child will sometimes buy something you consider ridiculous. Let that happen when the risk is reasonable.
When one of Sue’s sons wanted to spend an early paycheck on a fly-fishing rod, it was not the choice she would have made. But it was not her paycheck. If he used the rod for years, it was a terrific purchase. If he regretted it three days later, that experience was also useful. Either way, the lesson belonged to him.
The goal is not to raise children who make your financial decisions. The goal is to help them learn how to make their own.
Every yes costs another yes somewhere else. When a child spends thirty dollars here, those same thirty dollars are no longer available over there. Children need to feel that tradeoff while the stakes are still small.
The difficult moment comes when they spend their money and immediately want something else. They say, ‘But I do not have any money.’ Correct. That is what happens when money is spent.
Resist the urge to replace the money or deliver a ten-minute speech. The empty wallet is already teaching the lesson. A teenager who spends everything over the weekend may have to skip a later activity with friends. That is uncomfortable, but it is manageable and memorable.
Allowing a consequence is not abandonment. You can stay available, help your child think, and ask useful questions: What would you do differently next time? Was the purchase worth it? What options do you have now? Support reflection without immediately removing the consequence.
Cash, savings buckets, and age-appropriate debit accounts can all give children practical experience. A debit card makes the limit concrete: if the money is not in the account, it cannot be spent.
Separate spending and saving into visible buckets. A child can decide that part of each gift or payment is available now and part is reserved for later. The system matters less than the repeated habit of choosing before spending.
If an overdraft fee or other small mistake occurs, use the real statement to explain what happened. Keep the stakes low, but do not hide the mechanics. Children learn by seeing how balances, transactions, fees, and timing work.
Children can accidentally learn that the only way to earn more money is to work more hours. Investing introduces a different idea: money can also be put to work over time.
Sue and her husband opened investment accounts for their children when they were teenagers and used a larger Christmas gift as the starting money. The gift was not immediately exciting because the kids could not spend it. Over time, watching interest, dividends, and account growth turned it into one of the family’s best financial lessons.
Sue called the growth ‘free money’ to keep the concept simple and memorable. She regularly encouraged the kids to check their accounts and notice the difference between the amount they deposited and the amount they now had. Years later, they share investment ideas in the family group chat and use what they learned to support adult goals such as travel and homeownership.
You do not need to be an investing expert before you begin teaching. You need enough knowledge to help your child start, ask questions, and learn alongside you.
Current family-focused options include Fidelity Youth Account for teens ages 13 to 17, Greenlight’s parent-supervised investing tools, and BusyKid’s integrated saving and investing features. Products, fees, eligibility, and features change, so research the current terms and decide what fits your family before opening an account.
The starting amount does not have to be large. A child can divide ten dollars among spending, saving, giving, and investing. The purpose is not to chase a quick return. It is to learn what each choice makes possible.
Financial literacy is not a one-time conversation. Children need ongoing training, real examples, and repeated practice.
Review statements together. Explain interest and fees. Talk about why you wait before a purchase, how you compare options, and what you are saving toward. When your child makes a mistake, stay curious instead of turning the moment into a character judgment.
You are not trying to control every dollar forever. You are giving your child the knowledge and experience to manage money without depending on you to make every decision. Let them earn it, spend it, save it, and grow it while the stakes are still small. Those ordinary experiences can become the foundation for a capable, confident adult.
Note: This content is for educational purposes and is not financial advice. Account features, fees, eligibility, and investment options may change. Review current terms and consider professional financial guidance when appropriate.
Money is only one of the real-life skills children need to practice before they leave home. You do not have to control every choice or rescue them from every mistake. You can teach, set boundaries, and give them room to build confidence while the stakes are still small.
In Secrets to Parenting Without Giving a F^ck, Sue Donnellan shares practical tools to help you stop overfunctioning, set clearer expectations, and raise capable kids who know how to handle real life without yelling, overexplaining, or losing your mind.
Get practical advice from Sue delivered straight to your inbox.
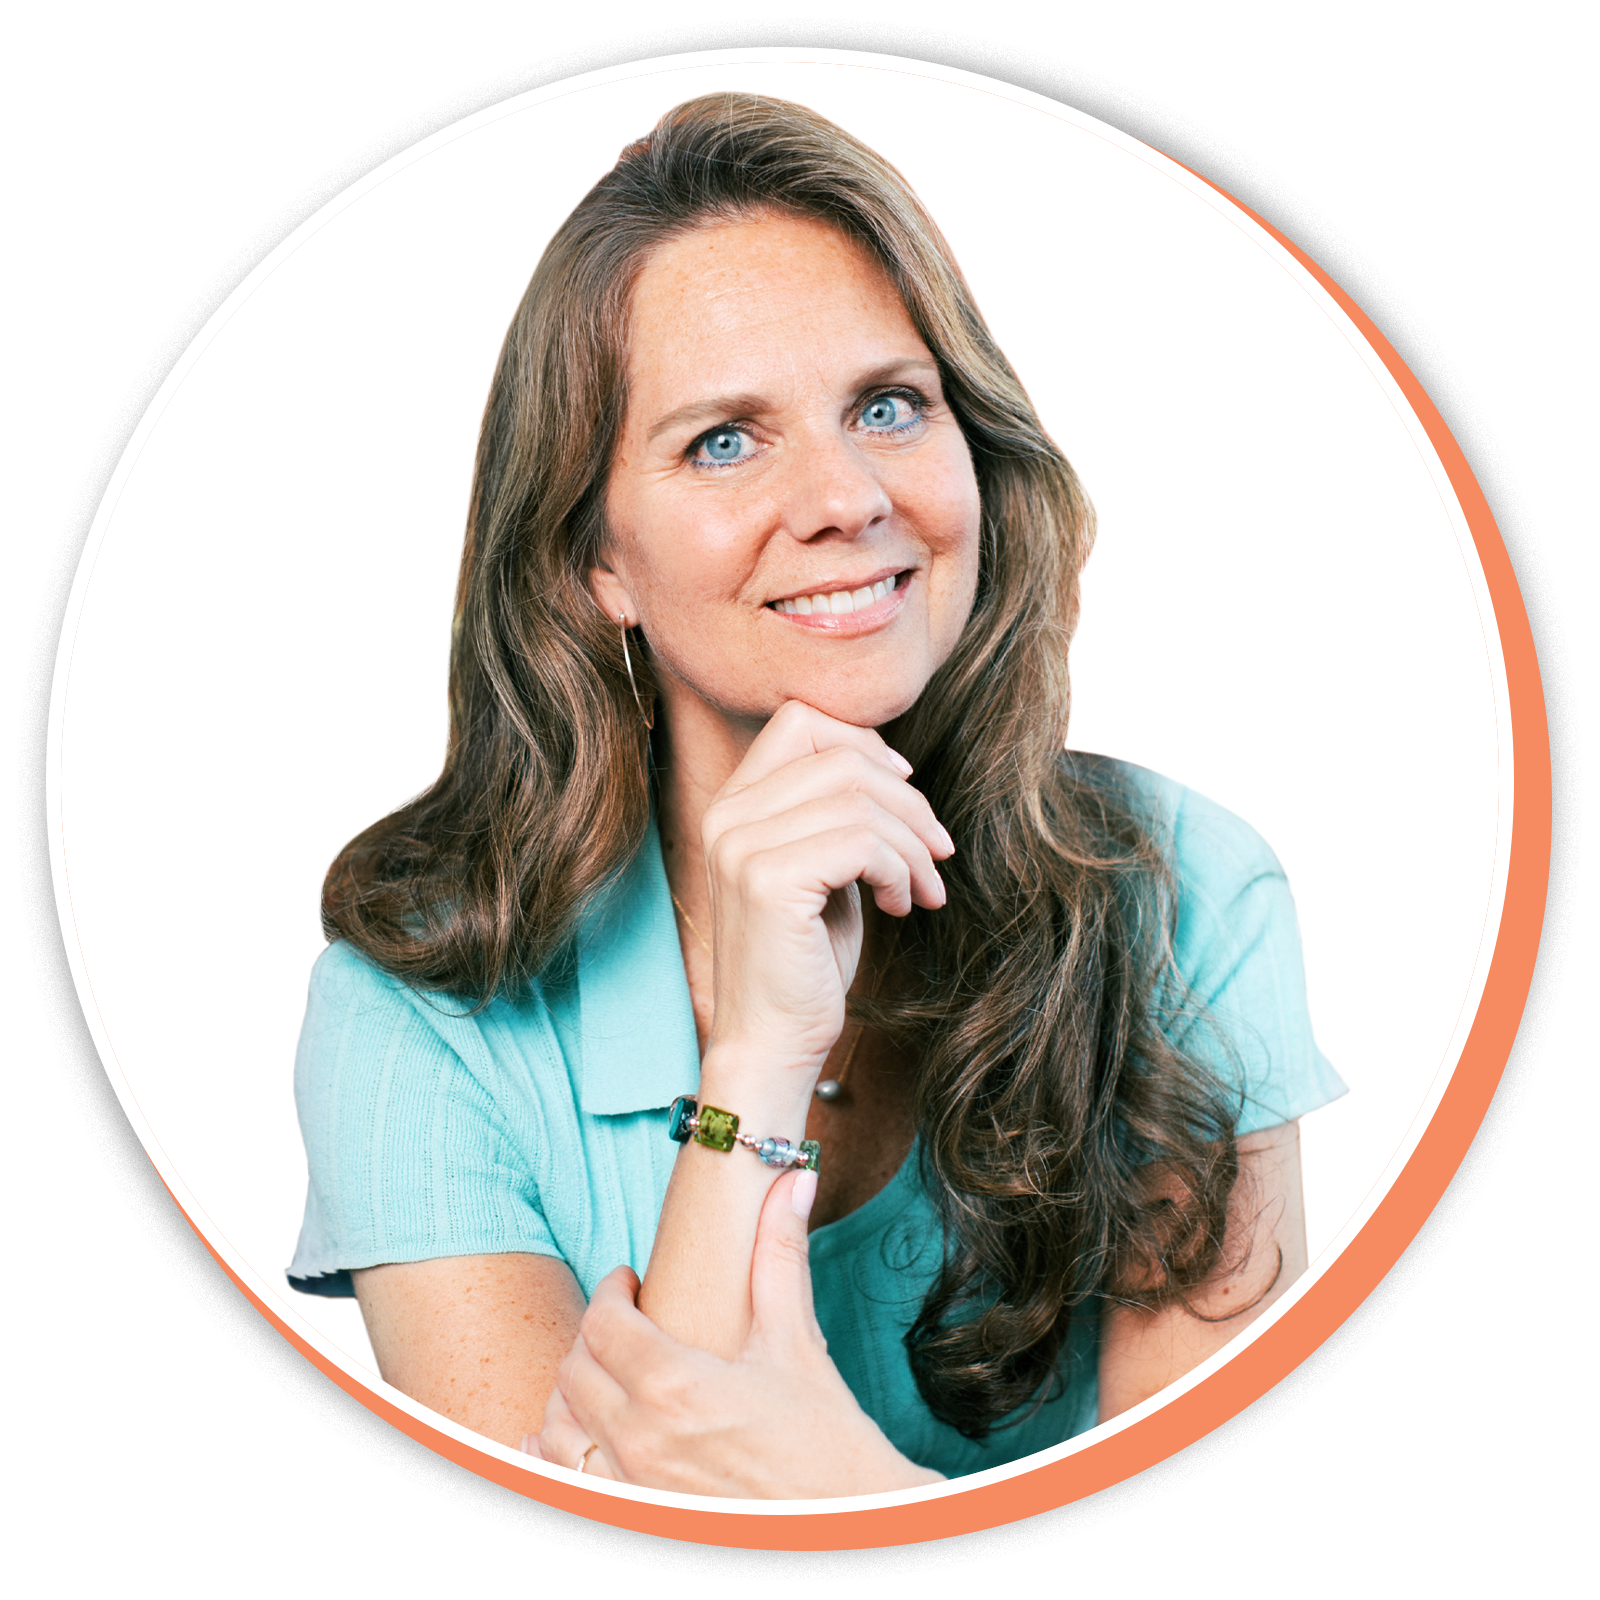
Sue Donnellan is a Parent Strategist & Educator. She’s a mom of four (including triplets), and the founder of Ask Mom Parenting. For more than 25 years, she’s cut through the guesswork for parents who have no village or anyone else to call. She helps parents raise kids who can think, cope, contribute, and eventually thrive on their own.
AI is no longer just helping teens with homework. Some young people are using chatbots for friendship, emotional support, romantic role-play, and conversations they do not feel...
When a teen lies, it can feel like a betrayal of everything you have tried to build. Your first instinct may be to confront, punish, lecture, or tighten control, but those...
Finding out your child is being bullied can bring up fear, anger, and an urgent need to fix everything. But stepping in too quickly can leave a child feeling powerless, while...